Loan borrower defaults: Who pays, what can banks seize? All your FAQs answered
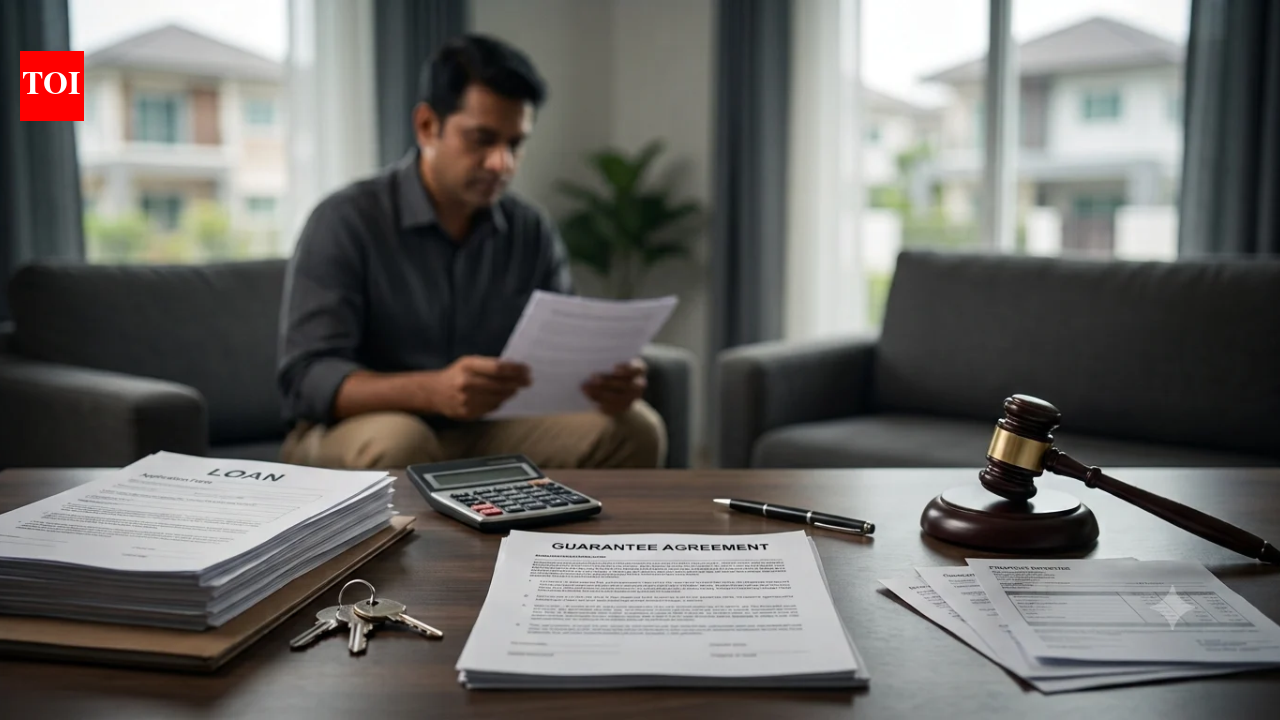
Thinking you're just a helpful signature? Think again. Being a loan guarantor is less 'wingman' and more 'human shield' for a bank. When the primary borrower does a financial disappearing act, guess who's left holding the bag – and potentially their own house keys – for the lender's convenience? It's the ultimate 'good deed' that can turn into a very bad, very expensive day, proving that sometimes, the best intentions pave the road to financial obligation.
Indeed, agreeing to guarantee a loan creates significant, immediate financial obligations, placing you directly in the lender's crosshairs if the borrower defaults. Lenders are legally empowered to pursue repayment directly from guarantors, often without first taking extensive action against the primary borrower or their assets. While this can feel like an unfair burden, guarantors do possess legal rights, including potential defenses or claims against the primary borrower; however, navigating these complexities requires prompt, informed action to protect one's assets and understand the full scope of liability.